The scarcest resource in the AI boom is not chips but capital: yields on CoreWeave's unsecured debt have reached 15% while the stock falls, so if funding costs ever outrun the spread it earns on renting out compute, the whole model unwinds.
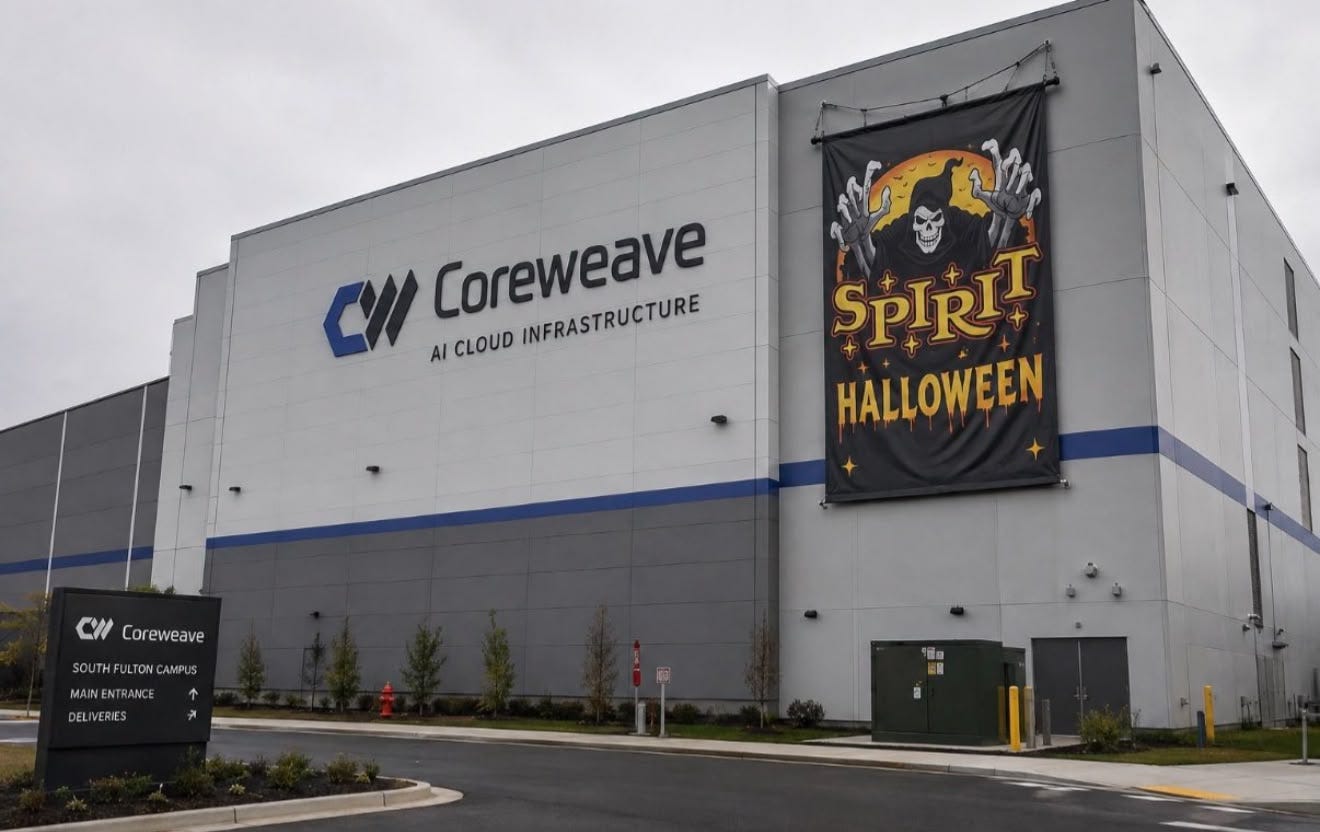
CoreWeave is not really a cloud company; it is a conduit to the capital markets. It started out mining Ethereum in someone's grandfather's garage in 2017, and now runs 51 data centres, yet it expects to spend $35bn to $39bn in 2026 alone just to keep expanding.
What I found most alarming is that yields on its unsecured debt have hit 15%. That means it has to earn more on the compute it leases out than it pays to borrow, and the moment that spread compresses, the model stops working.
Meta has said it will need to raise hundreds of billions of dollars over the coming years, and Musk timed SpaceX's June IPO to lock in $85.7bn before the competition. Next to them, CoreWeave is the first to look tired in this capital game.
Curated from high-quality sources, with concise summaries and key takeaways.

